Philadelphia 203k Contractor for FHA 203(k) Renovations
Buying a fixer-upper with an FHA 203(k) loan? MatrixGC is a renovation contractor that does 203(k) work every day. First, we write lender-ready bids. Then we work with your HUD consultant and lender, pull the permits and, finally, finish the job on schedule so your loan can close out.
- Philadelphia contractor license #43984
- Lender-ready bids
- Draw schedules handled
- Philadelphia & South Jersey
FHA 203(k) at a glance
Program limits from HUD. However, loan approval, rates and terms are set by your FHA-approved lender.
A certified Philadelphia 203k contractor
MatrixGC is a Philadelphia 203k contractor certified by the 203k contractors directory, licensed in Philadelphia (license #43984) and insured. We have been building FHA 203(k) renovations for Philadelphia buyers across row homes, twins and multi-family houses, and we work with buyers, realtors, lenders and HUD consultants every week.
- 203(k) is our specialty, not a side service. Lender-ready bids, draw schedules and consultant write-ups are part of every job.
- Philadelphia permits handled. Drawings, L&I filing and inspections, so draws are not held up.
- One team from walkthrough to final draw. Our own project manager on every 203(k) renovation.
What 203(k) clients say
I have recently completed a 203k project with Matrix Company. I would like to express my sincere appreciation for their team, who provided exceptional support throughout all phases of the project. Each team member was highly professional, consistently kept me informed, and sought my input on various details, ensuring I was fully engaged in the process. I was well-informed about all designs and materials used, and the results align perfectly with my preferences. I wholeheartedly recommend Matrix Company as a general contractor and had a very positive experience working with them.
 Zakeyah
I finally found the house that I wanted but it needed a lot of fixing up. Through Matrix, they got the job done via a 203(k) loan. When I first came into the house there were a lot of things that needed to be done. There were pipes missing, walls, the floors. Through Matrix, I got it accomplished. They even did extra work that was out of the budget
 Haffezah G
Limited vs. Standard 203(k)
Both loans roll the purchase and the renovation into one FHA mortgage. The difference is how big and how structural the work is.
Limited 203(k)
For cosmetic and system updates on a house that is structurally sound.
- Repair budgetUp to $75,000
- Structural workNot allowed
- HUD consultantOptional
- Best forKitchens, baths, floors, paint, roof, systems
Standard 203(k)
For gut rehabs and projects that change the structure.
- Repair budget$5,000 and up
- Structural workAllowed
- HUD consultantRequired
- Best forGut rehabs, additions, layout changes, major repairs
Still not sure which fits your house? See HomeStyle vs. 203(k) and our 203(k) FAQ.
What a 203(k) contractor does for you
- Walkthrough before you buy. That way, we help you understand what the house needs, ideally before your inspection deadline.
- Lender-ready bid. A detailed, line-item scope and price your lender and consultant can approve.
- Works with your consultant & appraiser. Then we align our bid with the consultant's work write-up.
- Permits. We pull Philadelphia or NJ township permits and schedule inspections.
- Draws & inspections. Next, we complete work in stages that match the lender's draw schedule.
- Final sign-off. Finally, we finish on schedule so the loan can close out.
203k loan calculator: estimate your loan and down payment
Enter the price and renovation budget for an instant estimate, then ask us for a free consultation.
Under contract on a fixer-upper? In that case, we can walk it and start your 203(k) bid this week.
How a 203(k) renovation works with MatrixGC
- 1. Get pre-approved with an FHA 203(k) lender. Try our free 203(k) qualifier.
- 2. Find the house and schedule a walkthrough with us.
- 3. Bid & write-up. We prepare the bid; the HUD consultant prepares the write-up (Standard).
- 4. Appraisal & closing based on the after-repair value.
- 5. Permits & construction, paid through the lender's draw schedule.
- 6. Final inspection and loan close-out.
Common 203(k) projects we handle
- Full gut rehabs of Philadelphia row homes
- Kitchen and bathroom remodels
- New roofs, windows, plumbing, electrical and HVAC
- Basement finishing and waterproofing
- Additions and 3rd floors (Standard 203(k))
- Fixing inspection and appraisal items. See resolving inspection issues with a 203(k).
Real estate agent or loan officer? If so, see our partner resources.
How to choose a 203(k) contractor
There is no official list of FHA-approved contractors. In fact, FHA does not approve or certify contractors; instead, your lender reviews and accepts the contractor for each loan. So when people search for an "FHA approved contractor," what they really need is a licensed, insured contractor who knows the 203(k) paperwork and whom the lender will accept. For example, lenders and HUD consultants typically look for:
- A valid contractor license and liability insurance
- A detailed, itemized bid that matches the work write-up
- Experience with the draw schedule and lender inspections
- References and completed 203(k) projects
- A realistic timeline the loan can support
MatrixGC is a licensed Philadelphia contractor (#43984). Because of that, we work with your lender and consultant from the first walkthrough to the final draw. See how long a 203(k) loan takes.
203(k) for 2 to 4 unit properties
A 203(k) loan can also be used on owner-occupied properties with two to four units. As a result, it is a popular way to buy and renovate a Philadelphia duplex or triplex. In addition, the scope and bid work the same way, with every unit included in the write-up.
203(k) projects in South Jersey
In addition, we also take on 203(k) and HomeStyle renovations in South Jersey towns such as Cherry Hill, Collingswood, Haddonfield and Voorhees.
Recent 203(k) renovations by MatrixGC
Real Philadelphia 203(k) projects. See full case studies: N Hollywood St, Webster St, Baltimore Ave, 7th St, Somerset St, Bristol Ave.
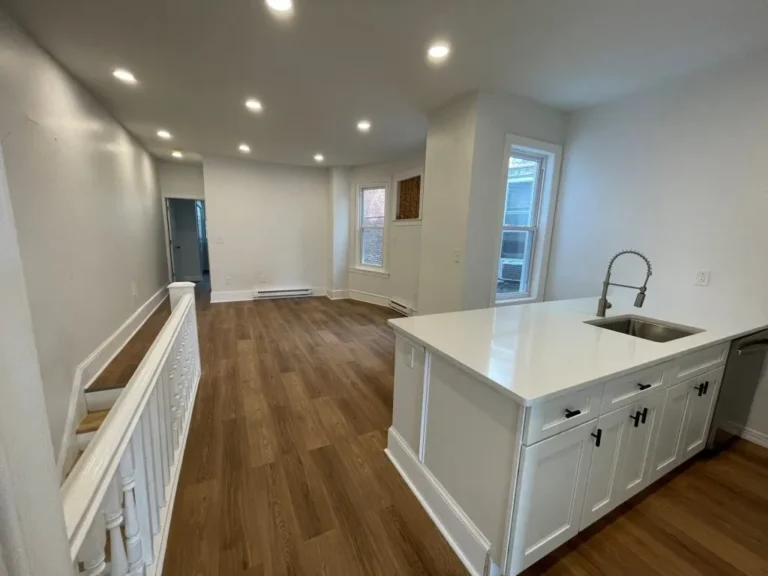
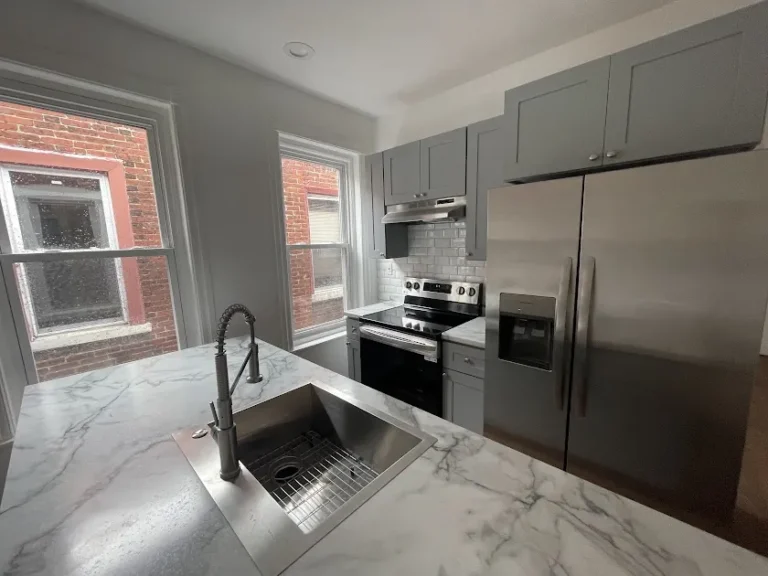
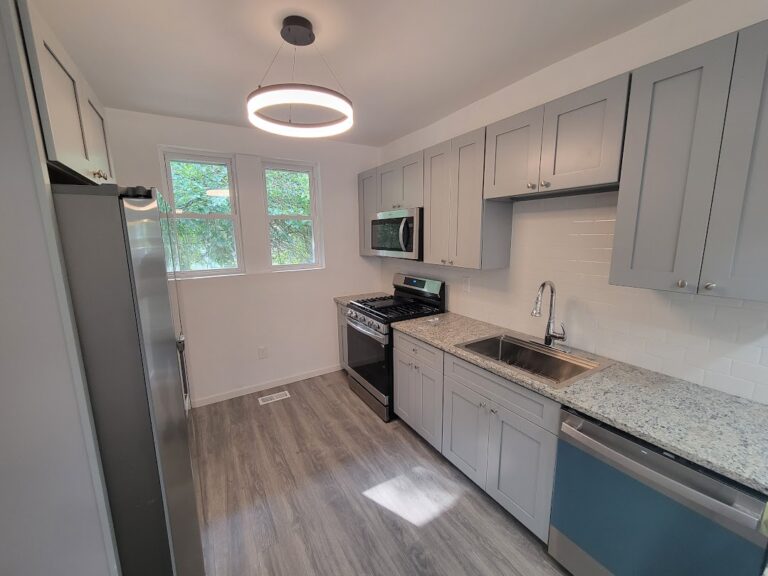
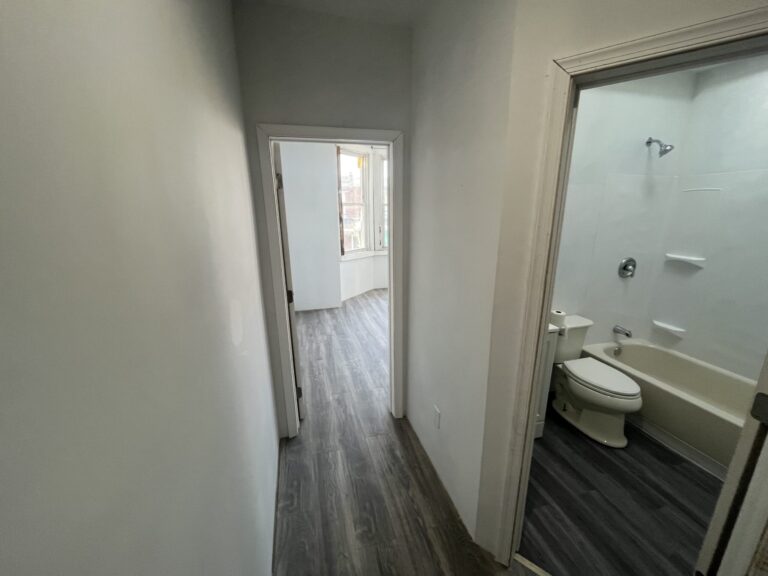
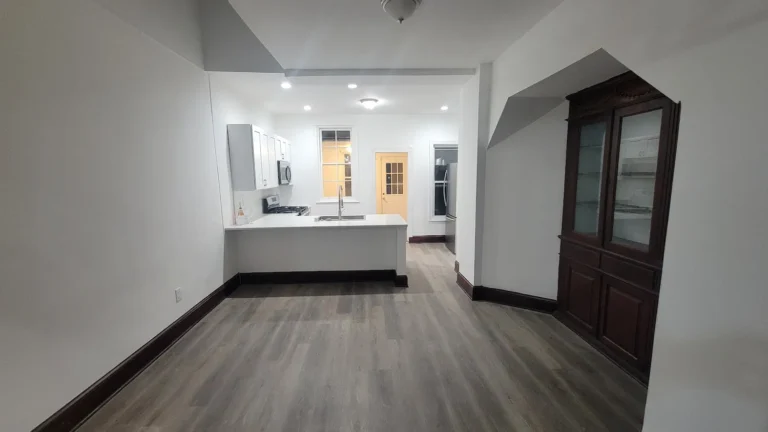
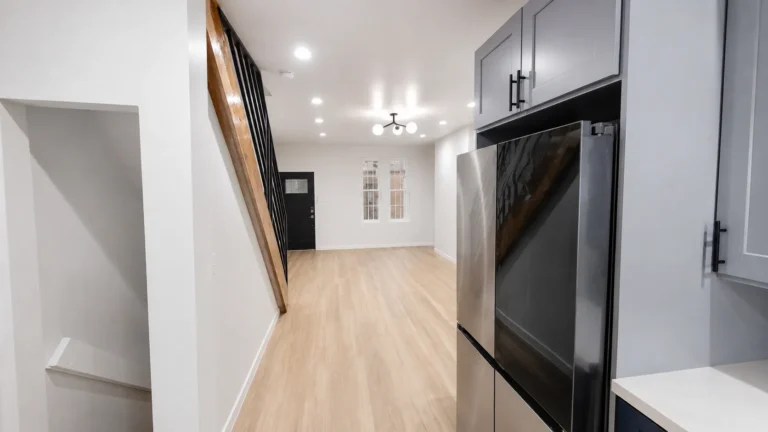
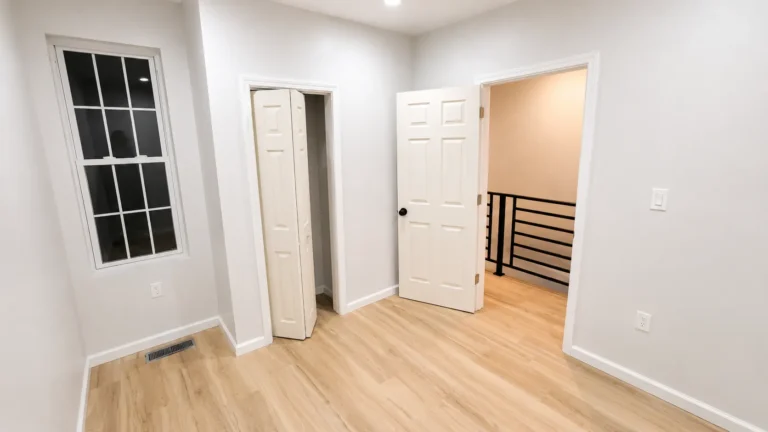
N Hollywood St
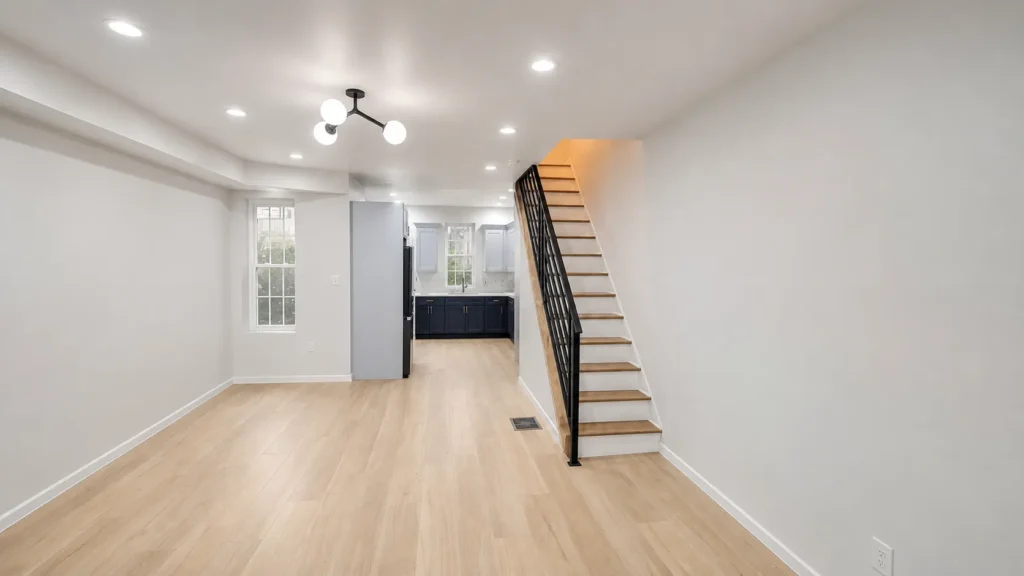
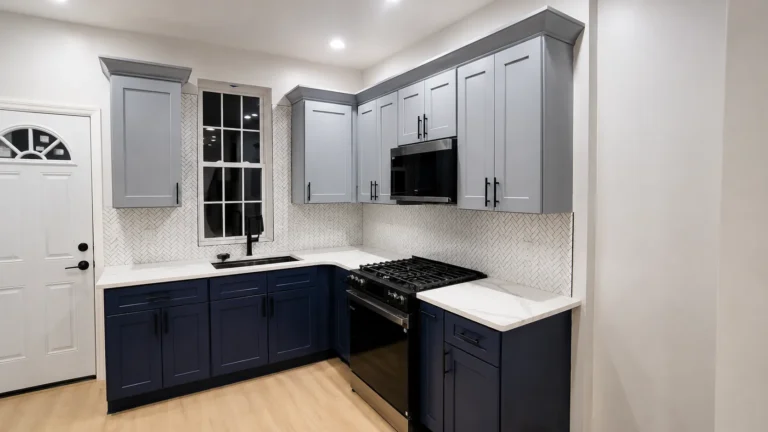
The first contractor left the job. We took over and finished the plumbing, electrical, kitchen, bathroom, flooring and painting.
Baltimore Ave
An investor used a 203(k) loan to turn a two-story house into a two-unit rental. We handled the bid, permits and build.
7th St
A new deck, a kitchen and bathroom remodel, a finished basement, new electrical, painting and flooring, all on one 203(k) loan.
Get a free 203(k) consultation
Found a house or still looking? Either way, tell us about it and we'll call to walk you through scope, budget and timeline.
Above all, talk to a 203(k) contractor before you lock your loan. Besides, the consultation is free.
203(k) guide library
Everything we have written about FHA 203(k) loans in Philadelphia, grouped by topic. Not sure a 203(k) fits? First, take our 2-minute 203(k) Qualification Wizard.
Start here
- A Complete Guide to FHA 203(k) Loan Requirements in 2026
- 203K Loan FAQs
- 203(k) Loan Financing Benefits: Save Deals, Customize, Build Equity
- 2025 203(k) Loan Update: Everything You Need to Know
- 2025 FHA Loan Limits in Philadelphia & New Jersey: Everything You Need to Know
- MPS for FHA vs. Conventional Loans: Key Differences Explained
- Can You Have Multiple FHA Loans? (2025 Guide)
Process and timeline
- FHA 203(k) Loan Timeline: How Long It Takes (2026 Guide)
- 7 Tips to Make the 203(k) Loan Process Smooth
- 203(k) Permit Process in Philadelphia
- How to Do a Quick 203(k) Feasibility Study (Contractor’s Guide for Homeowners)
- Closing a 203(k) Project: Finalized Permit Vs. Certificate of Occupancy
- Complexities of a 203(k) Renovation: Wagon Trains and 203(k) Projects
Costs and budget
Inspections and appraisal
- A Home Inspection for a 203(k) Loan: Is it Required?!
- FHA Appraisal vs. Home Inspection: Complementary Roles in a 203(k) Loan
- How to Determine Property Value in Philadelphia for 203(k) Loan Appraisals
- Overcoming Appraisal Issues with a 203(k) Loan: Unlock 110% Financing
- Resolve Home Inspection Issues with a 203(k) Renovation Loan
Compare renovation loans
- HomeStyle Vs. 203(k) loan
- Choosing Between a 203(k) and HomeStyle Loan for Philadelphia Multi-Family Dwellings
- How to Navigate the Fannie Mae HomeStyle Loan Process?!
- Conventional Renovation Loans: Your Guide to Financing a Renovation
- A Complete Guide to Overcoming the Challenges of Reno Loans for Realtors
Project ideas
- Possible Home Additions with a 203(k) Loan in the Philadelphia Metro Area
- How to Convert a House to a Duplex in Philadelphia (2026 Guide)
- 203(k) Renovation for Mixed Use Property or Commerical Space
- 203(k) Loan for Manufactured Homes
- 5 Reasons Why 203(k) Renovations Are Perfect for Philadelphia's Historic Homes
- Transforming Your Philadelphia Home with Smart Home Technology and a 203(k) Loan
- Mortgage Free Life in Philadelphia and South Jersey with 203(k) Loan
- The Top 7 Mistakes Homeowners Make When Choosing a Philadelphia 203(k) Loan Contractor
A 203k construction company that runs the whole project
Most 203k contractors only do the construction. As a 203k construction company and 203k rehab contractor, MatrixGC also handles the parts that slow loans down: the scope of work, the bid package your lender and consultant need, and the draw schedule.
- Bids your lender accepts. Itemized to match the 203k consultant's write-up.
- Permits and inspections. Filed and scheduled by us.
- Philadelphia and New Jersey. We work with 203k buyers, lenders and realtors on both sides of the river.
In New Jersey? We also offer 203k contractor in South Jersey, across Camden, Burlington and Gloucester counties.
203(k) contractor FAQ
203(k) loan basics
What is an FHA 203(k) loan?
An FHA 203(k) loan lets you finance the purchase or refinance of a home and the cost of renovating it in one FHA-insured mortgage. For instance, the Limited 203(k) covers up to $75,000 of non-structural repairs. In contrast, the Standard 203(k) covers larger projects, including structural work, with a minimum of $5,000 in repairs.
Do I need a 203(k)-approved contractor?
HUD does not issue a contractor certification. However, your lender must approve your contractor. Therefore, you need a licensed, insured contractor who can produce lender-ready bids, work with a HUD consultant and complete work on a draw schedule. That is exactly what we do every day.
What is the difference between Limited and Standard 203(k)?
Limited 203(k) is for non-structural repairs up to $75,000, and a HUD consultant is optional. On the other hand, Standard 203(k) is for larger or structural projects with at least $5,000 in repairs, so it requires a HUD-approved consultant.
Payments, timing and New Jersey
How do contractors get paid on a 203(k)?
Through draws. In other words, the lender releases funds in stages as work is completed and inspected, according to the schedule set at closing.
Can I use a 203(k) in South Jersey?
Yes. FHA 203(k) is a federal program, so it is also available in New Jersey. As a result, we work on 203(k) projects in both Philadelphia and South Jersey.
How long does a 203(k) renovation take?
It depends on scope. For example, a Limited 203(k) with cosmetic and system work may take a few weeks, whereas a Standard 203(k) gut rehab often takes several months. Meanwhile, your lender sets the completion deadline, and we schedule the work to meet it.
Credit, license and approval
What credit score do I need?
Requirements are set by the lender. Generally, many FHA lenders look for a credit score of 580 or higher for the 3.5% minimum down payment. To see where you stand, try our free 203(k) qualifier.
Are you licensed and insured?
Yes. MatrixGC holds Philadelphia contractor license #43984 and is insured. Also, we provide the license and insurance documents your lender requires.
Is there a list of FHA-approved 203(k) contractors?
No. FHA does not approve or list contractors. Instead, your lender reviews and accepts the contractor for each loan. Therefore, choose a licensed, insured contractor with 203(k) experience and a detailed, itemized bid.